ACN / FQ4 2026 - Aug 2026
Accenture plc
Reports Oct 1 · Before 8:00 AM ET
Publication status
Awaiting results
Sep 28, 2026, 9:00 AM PDT
Shortcut EPS
3.15
USD per share
Street EPS
3.18
USD per share
Actual EPS
—
Pending
Financial workbook
Explore the model.
Explore the assumptions and calculations behind this earnings forecast.
ACN · Workbook preview
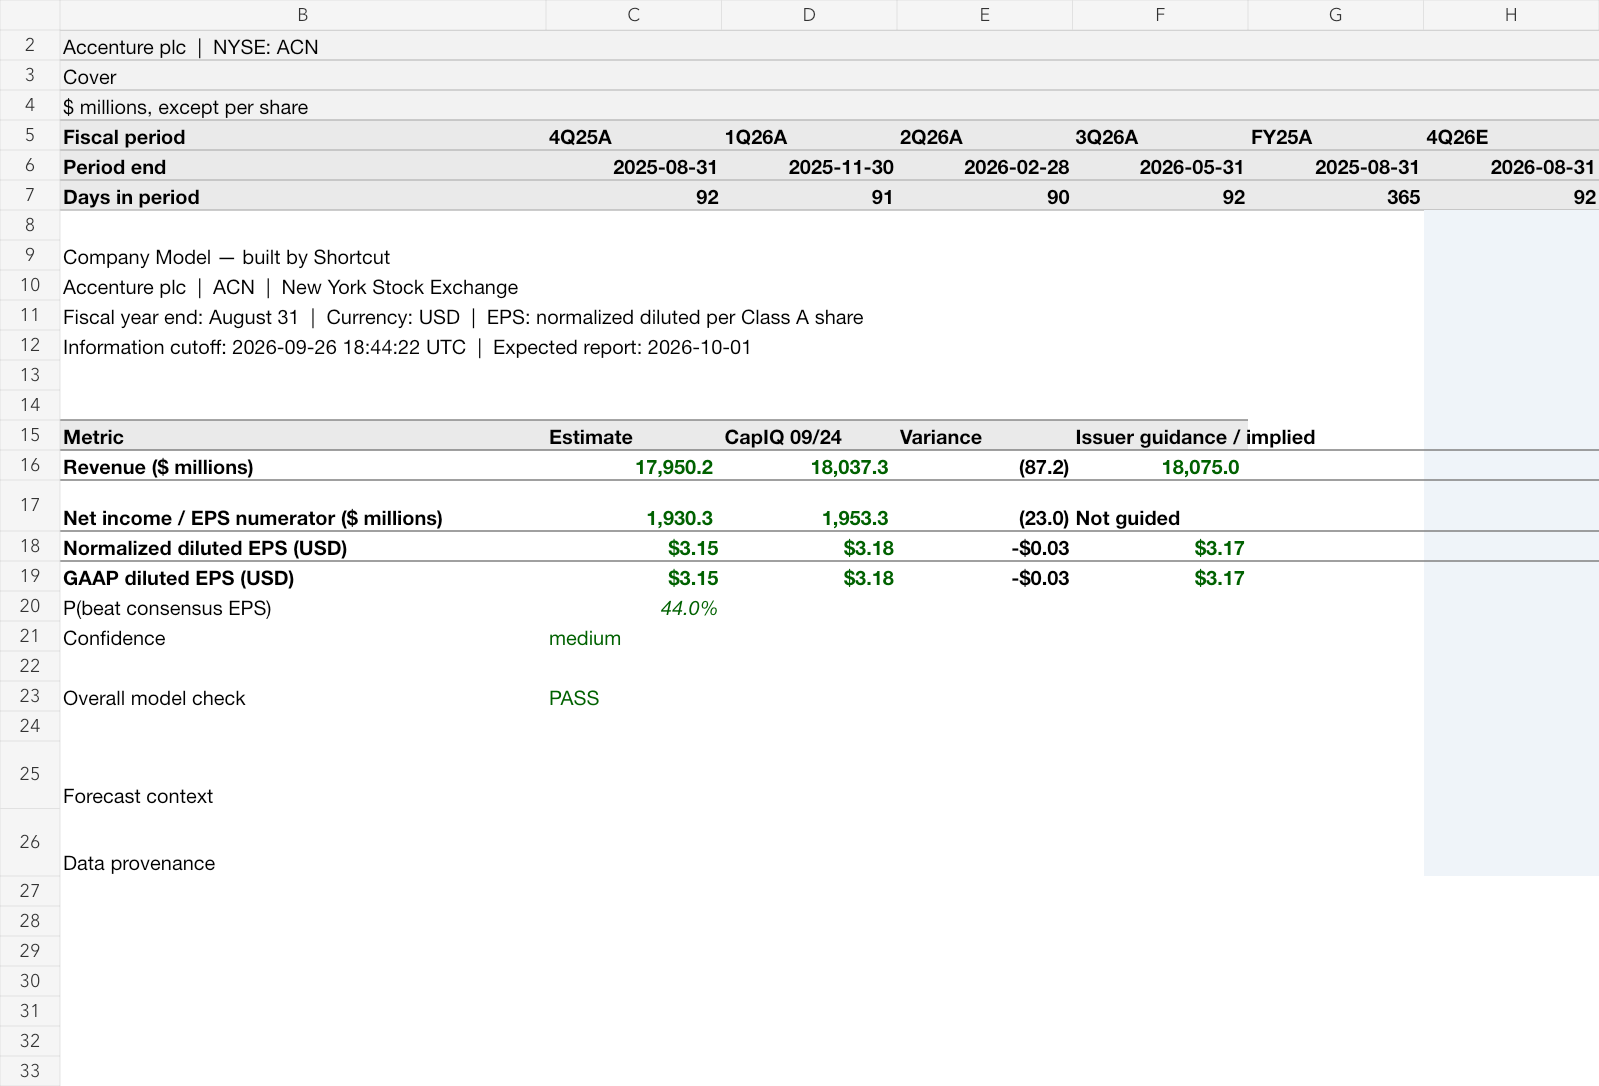
What drives the forecast
- June 18 issuer fourth-quarter revenue guidance was $17.75–18.40bn; the $17.95bn model sits $0.13bn below its $18.075bn midpoint amid disclosed macro uncertainty and Middle East consulting disruption.
- The Q3 FY2026 issuer 10-Q reported $18.718bn revenue, $19.32bn bookings and $3.80 GAAP EPS; Q3 managed services local-currency growth of 5% exceeded consulting at 1%.
- The June full-year adjusted EPS guidance midpoint of $13.84 implies roughly $3.17 in Q4 after Q1–Q3 adjusted EPS; the modeled $3.148 EPS is a modest negative tilt, not a double-digit deviation.
- The September 18 pre-report preview counted 19 negative and zero positive Q4 revenue revisions over three months; its EPS beat history and the issuer's repurchases temper the downside probability.
- The six CapIQ historical quarters show consistent normalized EPS beats, but the preceding Q3 revenue missed estimates; Q4 EPS beat probability is 44%, below 50% in line with the model's below-consensus EPS.
- EPS basis: Normalized equals GAAP in this model; no business optimization charge assumed.
The Street baseline: CapIQ export, September 24, 2026. Results are scored only after the earnings basis is matched. Read the methodology.