MKC / FQ3 2026 - Aug 2026
McCormick & Company, Incorporated
Reports Oct 1 · Time not specified
Publication status
Awaiting results
Sep 28, 2026, 9:00 AM PDT
Shortcut EPS
0.74
USD per share
Street EPS
0.76
USD per share
Actual EPS
—
Pending
Financial workbook
Explore the model.
Explore the assumptions and calculations behind this earnings forecast.
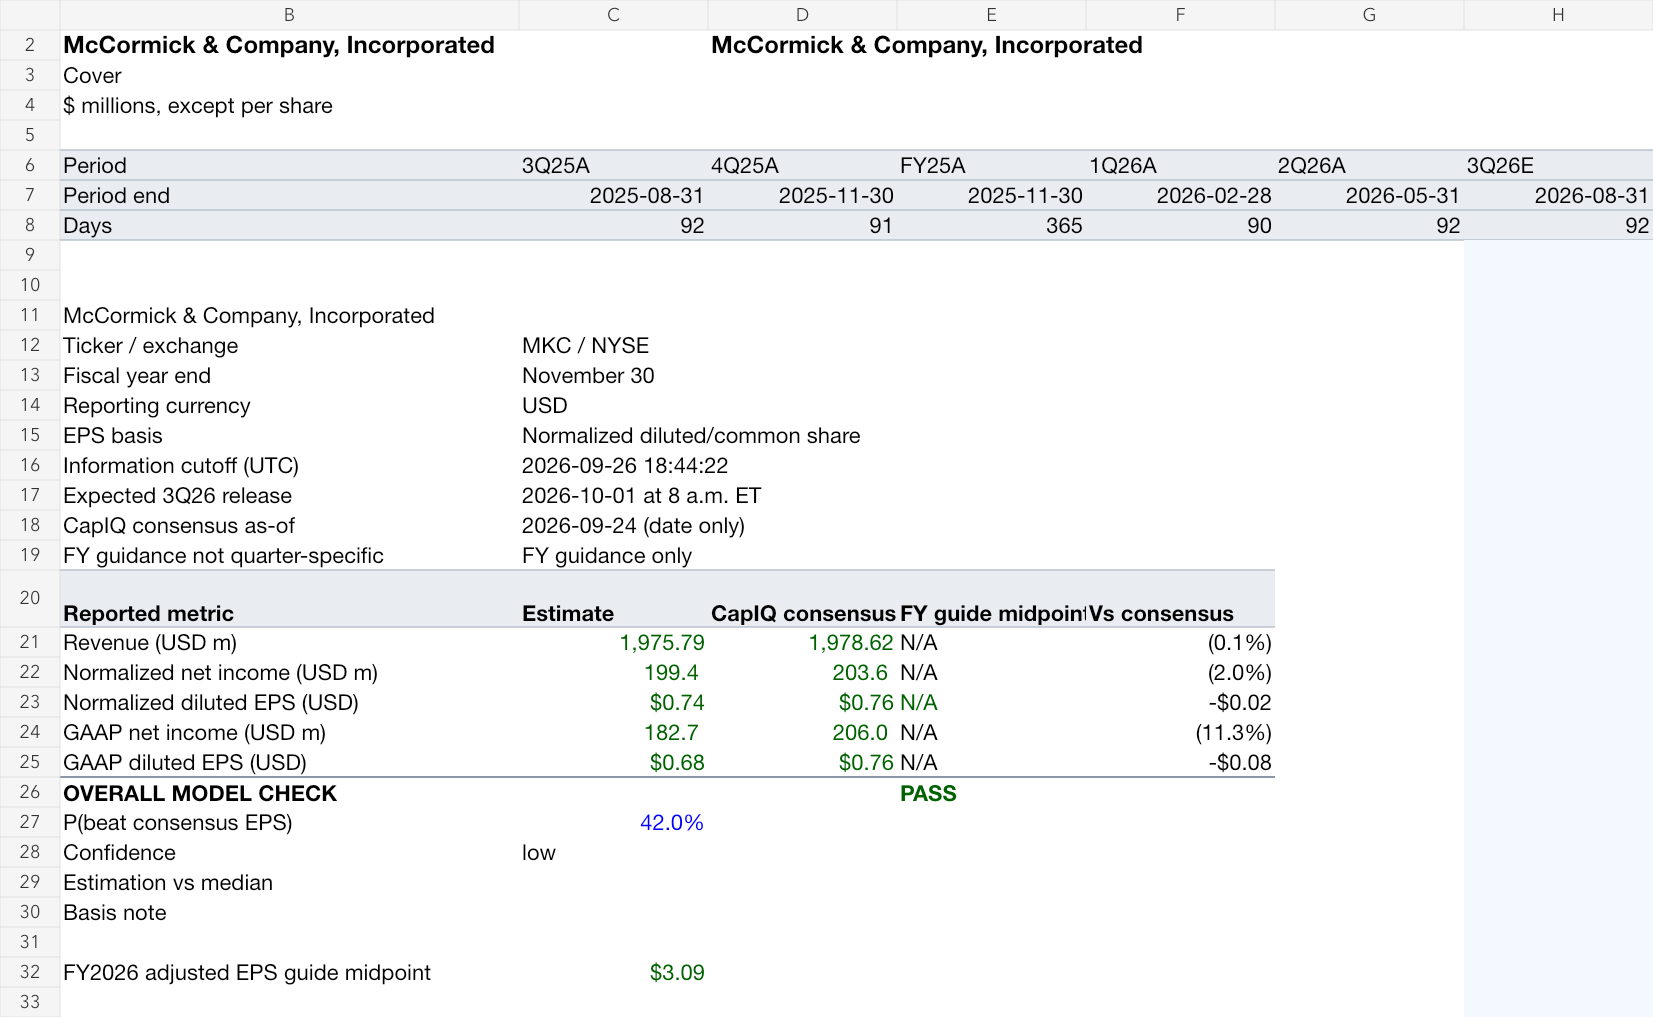
MKC · Workbook preview
What drives the forecast
- Q2 sales grew 16.7%, but Consumer Americas organic sales contracted 0.2%; management expected sequential consumer volume improvement, with execution risk (June 25 issuer release).
- Forecast Consumer revenue $1,171.9m and Flavor Solutions $803.9m, including the previously known Mexico consolidation; total $1,975.8m is just 0.1% below September 24 CapIQ consensus.
- Q2 gross margin included a $28m tariff refund, approximately 140bp; assume 38.2% Q3 gross margin without repeating that one-off benefit (June 25 issuer release).
- Zacks September 24 EPS preview reported a -1.97% most-accurate-estimate ESP and Sell rank; this offsets recent positive earnings surprises and supports $0.74 versus $0.76 CapIQ normalized consensus.
- Issuer FY2026 adjusted EPS guidance $3.05-$3.13 was reaffirmed June 25; no quarter-specific guidance. Mexico noncash remeasurement gain belongs only to 1Q26, not the forecast quarter.
The Street baseline: CapIQ export, September 24, 2026. Results are scored only after the earnings basis is matched. Read the methodology.