MU / FQ4 2026 - Aug 2026
Micron Technology, Inc.
Reports Sep 30 · Time not specified
Publication status
Awaiting results
Sep 28, 2026, 9:00 AM PDT
Shortcut EPS
31.65
USD per share
Street EPS
31.60
USD per share
Actual EPS
—
Pending
Financial workbook
Explore the model.
Explore the assumptions and calculations behind this earnings forecast.
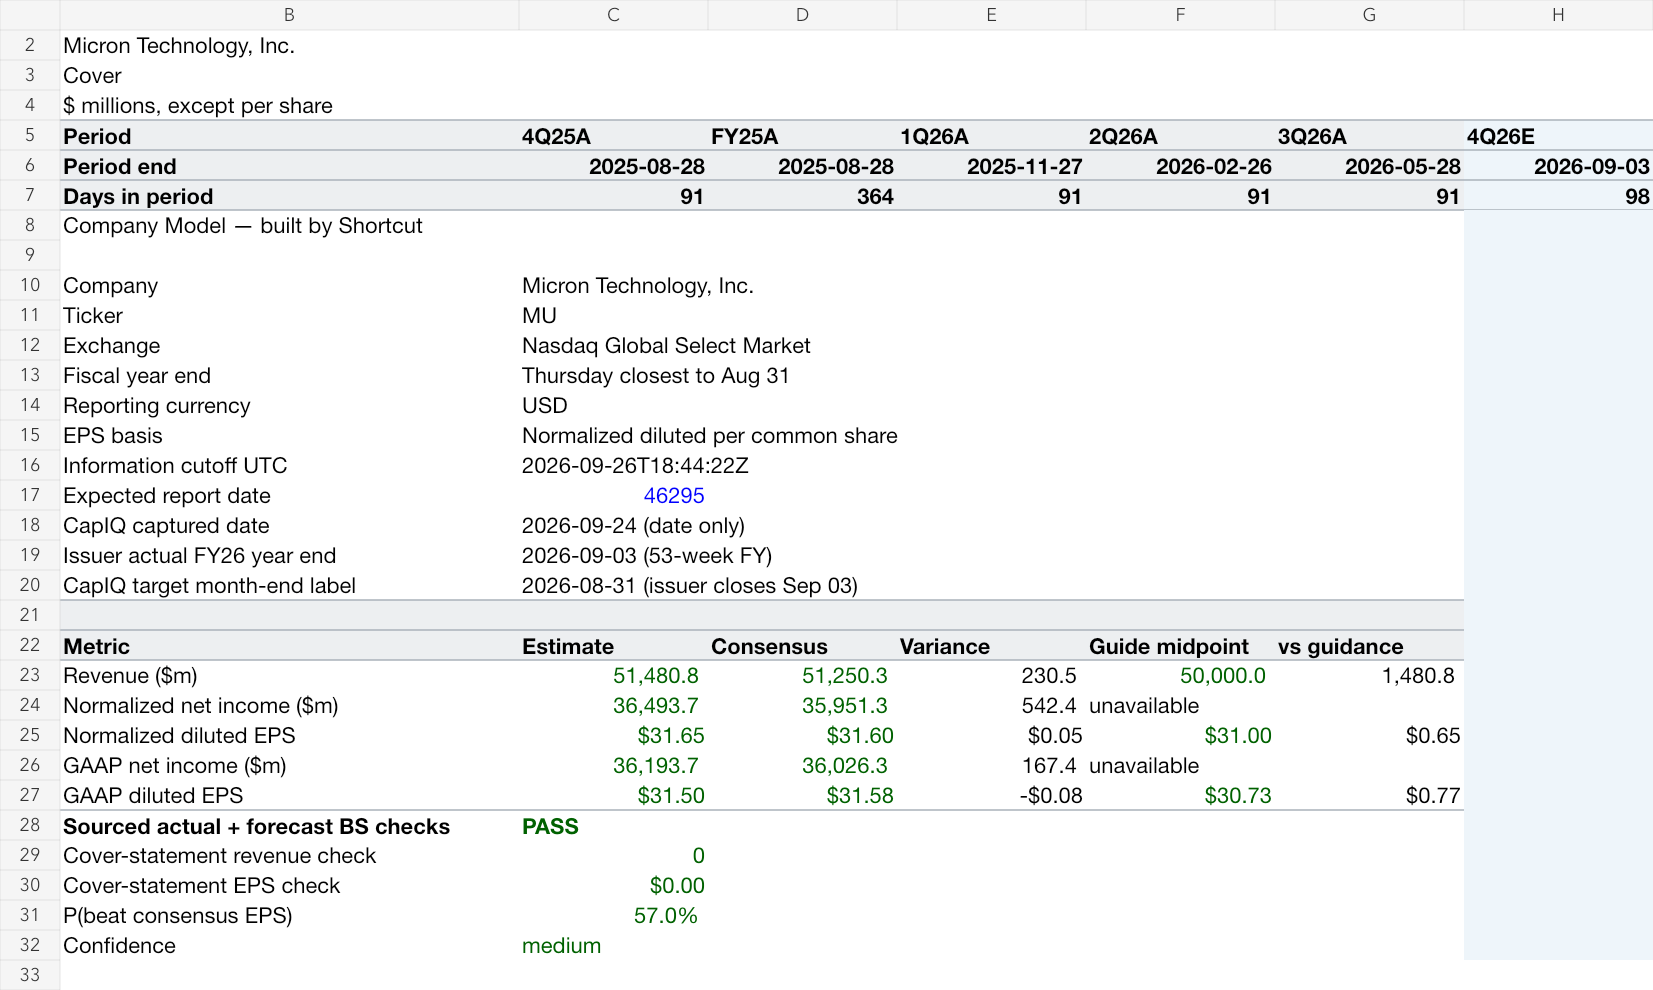
MU · Workbook preview
What drives the forecast
- September 24 CapIQ consensus is $51,250.26m and $31.60 normalized diluted EPS (33 normalized EPS estimates); $51,480.78m and $31.65 are deliberately only slightly above those benchmarks.
- Micron's June 24 pre-release outlook guided $49bn-$51bn revenue, ~86% gross margin and $30-$32 non-GAAP diluted EPS; Q1-Q3 FY26 reported revenue and adjusted EPS each exceeded guidance midpoints, but consensus already embeds guide upside.
- The May 2026 10-Q confirms a 53-week FY26 with a 14-week Q4; forecast unit revenues use reported Q3 segment sales, 98/91 day normalization, and explicitly modeled shipment and pricing changes.
- TrendForce projected 13%-18% third-calendar-quarter DRAM contract price increases despite moderating price momentum; SK hynix reported strong AI-memory pricing. September 24 Citi commentary modeled $51bn revenue and $31.45 EPS, below the supplied normalized EPS mean and an important miss risk.
- Modeled 86.1% GAAP gross margin, $1.86bn GAAP operating expense, 15% tax, 1,149m GAAP and 1,153m non-GAAP diluted shares yield $31.50 GAAP and $31.65 normalized EPS. The supplied Aug 31 target label is not Micron's actual Sep 3 fiscal year end.
The Street baseline: CapIQ export, September 24, 2026. Results are scored only after the earnings basis is matched. Read the methodology.