RPM International
Oct 4, 2026, 9:26 PM PDT
Shortcut EPS
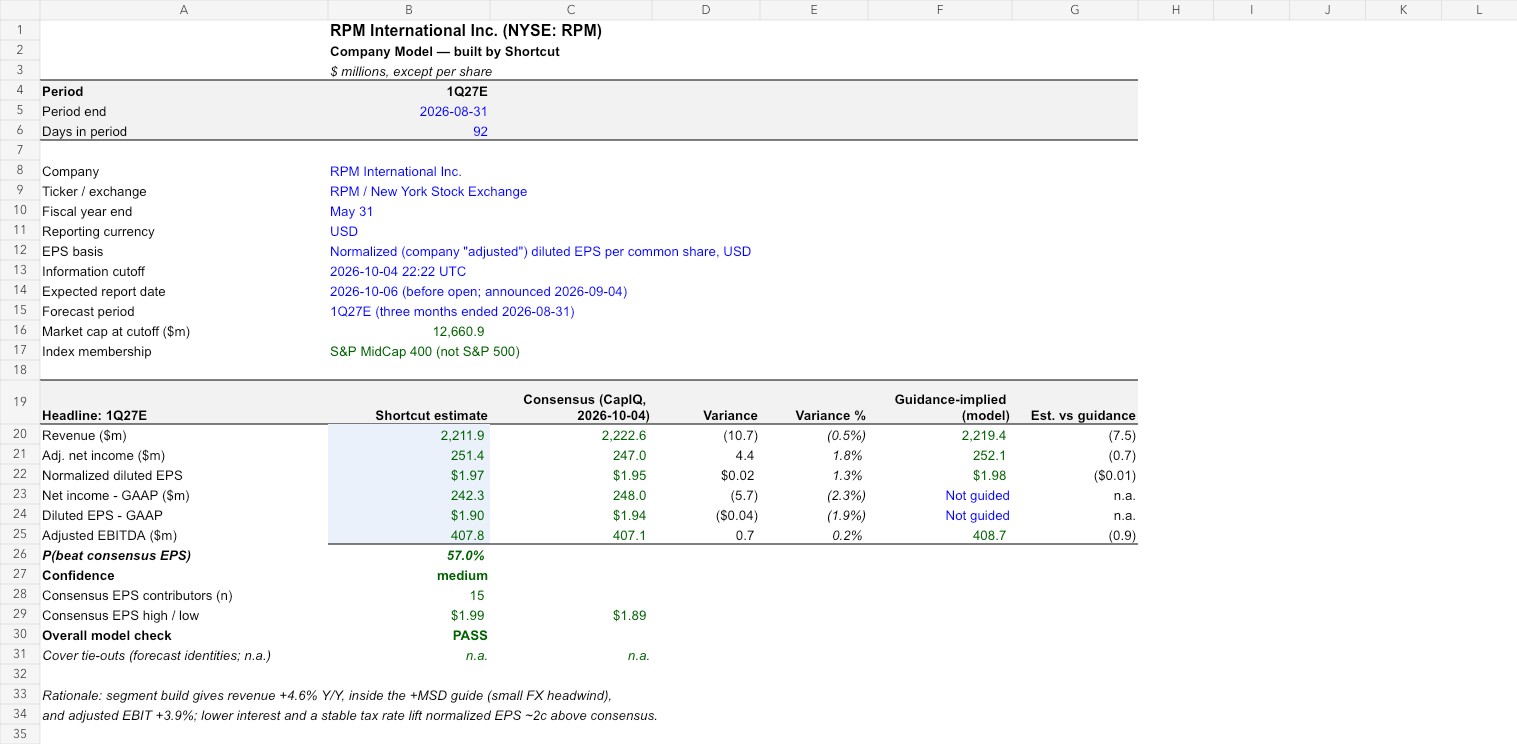
1.97+1.3% vs Street
Street EPS
1.95Frozen October 4 snapshot
Actual EPS
—Awaiting earnings
Explore the model.
Open the assumptions and calculations behind this earnings forecast.
Behind the estimate.
The segment build projects $2.21bn of revenue, up 4.6%, and $408m of adjusted EBITDA, up 4.8%. Cost savings and construction-product volumes partly offset raw-material inflation, supply disruption and soft DIY demand.
The model assumes $27m of interest expense, $6.5m of core investment income, a 23.8% tax rate and 126.9m diluted shares, producing normalized EPS of $1.97.
The forecast retains assumptions about participating-share allocation and buyback timing. These assumptions affect EPS by less than about $0.002 in the reviewed sensitivities.
The workbook was forecast and independently reviewed with Opus 5.5 High. The estimate remains a forecast, including the assumptions described here.
On the record.
- Reporting period
- Q1 FY2027, ended 2026-08-31
- Reporting basis
- Normalized diluted EPS, USD per common share
- Information cutoff
- October 4, 2026, 22:22 UTC
- Published
- Oct 4, 2026, 9:26 PM PDT
- Model / effort
- Opus 5.5 · High effort
Consensus capture has date-only precision. Research used live retrieval of sources published by the cutoff, with no archived page snapshots. Original forecasts, models and publication times remain on the record.