M&T Bank
Oct 12, 2026, 2:36 AM PDT
Shortcut
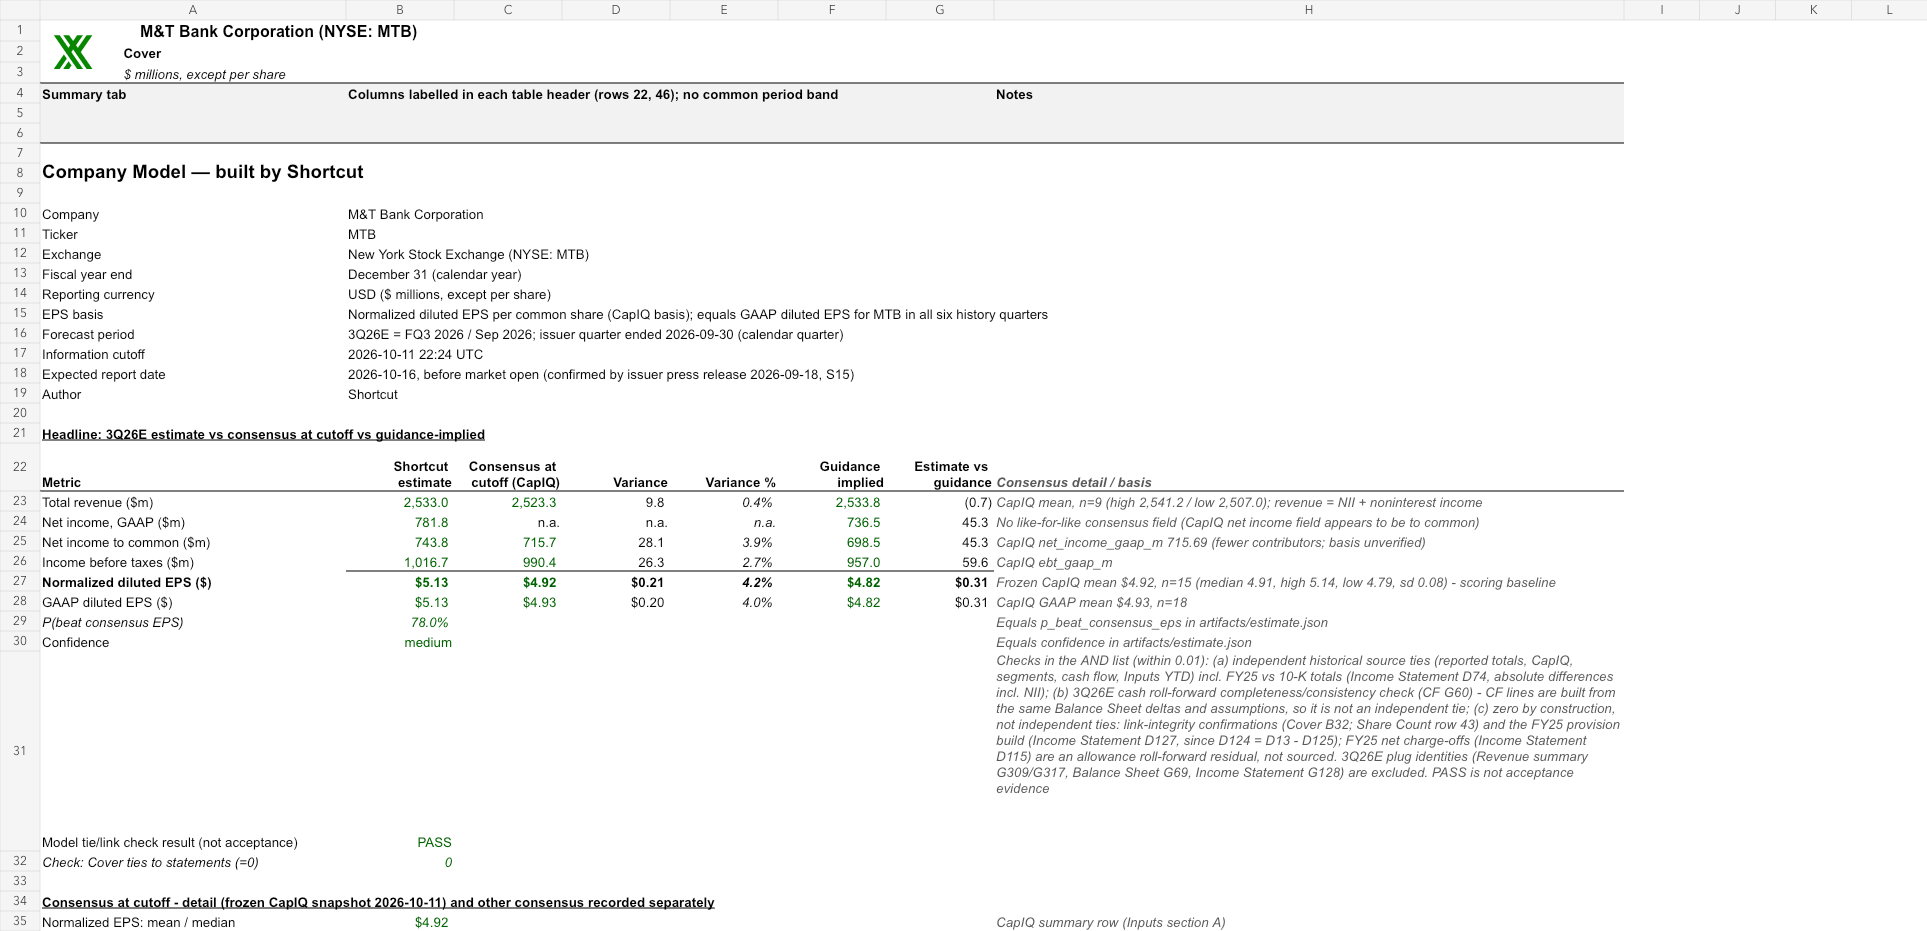
5.13Shortcut normalized EPS
+4.2% vs Street*
Street
4.92Street normalized EPS
Frozen October 11 snapshot
Real
5.04Reported diluted EPS
Shortcut win
Shortcut off by $0.09 · Street off by $0.12.
Uses reported diluted EPS of $5.04, consistent with the original model’s GAAP-equivalent normalized basis. The separate $5.08 net operating EPS adds back intangible amortization. The score compares published values; exact normalization matching remains unverified.
Issuer earnings release ↗Explore the model.
Open the assumptions and calculations behind this earnings forecast.
Behind the estimate.
The model forecasts $5.13 per diluted share for the quarter ended September 30, 2026.
Forecast and independent review: Opus 5.5 High in Shortcut.
Model assumptions and review notes
- Modeled normalized EPS; comparability with the frozen Street definition remains unconfirmed. The score compares published values directly.
- F01 normalized comparator basis: normalized = GAAP is inferred from six history quarters. A CDI-addback basis gives +$0.0318 (5.1597, IS G87). Excluding the $1m securities gain gives -$0.0053.
- GAAP ETR 23.1% vs consensus ETR 24.03% (basis unverified): -$0.0701 per +1pp; about 5.063 at 24.03%. Retained judgment.
- F03 average-balance judgments: about +$0.004 net if all aligned to EOP midpoints (ST borrowings +$0.0205, IB deposits -$0.0044, HFS -$0.0032, loan timing -$0.0086).
- F04 sub-servicing yield: $0.0246 EPS per bp of RS G178.
- F02 4Q25 basic shares (implied 152.44m vs back-out 152.66m): no EPS dependency.
- F07 FY25 NCO residual (553) is unsourced: no EPS dependency; the Guidance H14 verdict flips at 541 or lower.
- F09 average_loans tracked basis: HFI 143,700 vs incl. HFS 144,400. Issuer FY26 guide basis unconfirmed.
- F06 P(beat) override of -2.3pp is not itemized; market cap retrieved after the cutoff (published 2026-10-09).
- Web sources S11, S13 and S19-S22 were published before the cutoff but retrieved 2026-10-12 without archived snapshots (documented limitation, not a post-cutoff source).
- normalization treatment for 3Q26 is unverified. The model assumes normalized = GAAP (IS G78:G80 = 0). Sensitivity is $0.0053 EPS per $1m pre-tax adjustment.
- 4Q25 weighted basic shares (Share Count C10) are implied from rounded EPS. A day-weighted 10-K back-out gives 152.664m (EPS 4.70). There is no forecast EPS dependency.
- 1Q26 computed basic EPS of 4.1548 versus reported 4.16 appears to be $m rounding (it needs NIAC of at least 620.03). This is unconfirmed, with no forecast EPS dependency.
- Sub-servicing fee yield: the 2Q26 average UPB is a simple average despite late-quarter boarding. Sensitivity is $0.0246 EPS per bp; the 17.90bp 1Q26 yield would add +$0.0099.
- 3Q26E average balances versus the EOP path are retained judgments. Sensitivities: short-term borrowings +$0.0205, IB deposits at banks -$0.0044, HFS -$0.0032.
- Other earning assets: whether the S7 dash for 2Q26 means nil or a reclassification is unconfirmed. Exposure is about +$0.0044 EPS if roughly 95 persisted.
- Final P(beat) override of -2.29pp (0.8029 to 0.78) is not itemized in the saved calibration file. S&P 500 membership rests on the flag only; the large bucket holds regardless (31.41bn > $10bn).
- All sources were retrieved after the cutoff without snapshots, so post-cutoff edits to S11, S13 and S19-S22 cannot be excluded.
- 3Q24/4Q24 Y/Y comparators are on a pre-recast, mixed basis. The recast effect on 2024 totals is unavailable.
- No frozen panes exist on any of the 12 sheets, so none need removal.
- This audit does not certify the model as clean. Publication should carry the caveats above.
On the record.
- Reporting period
- Q3 2026 (quarter ended September 30, 2026), ended 2026-09-30
- Reporting basis
- Normalized diluted EPS per common share, USD (basis; equal to GAAP diluted EPS for MTB historically). 'Income Statement'!G81 = SUM(G77:G80) = G70 + notable-item adjustments (all 0). G70 = net income available to common 743.8228 / diluted shares 145.0552m. Net income available to common = net income 781.8228 - preferred 36 - unvested awards 2.
- Published
- Oct 12, 2026, 2:36 AM PDT
- Model / effort
- Opus 5.5 · High effort
Original forecasts, models and publication times remain on the record.